House-Hacking and Rental Property Basics
By Yuanming Mao, DRE #02242767 · Navigators Real Estate, Inc.
How ADUs and small multi-unit properties can offset mortgage costs in high-priced California markets, and what to verify before you buy or build.
Housing costs in Southern California can feel like a wall. Yet a growing number of younger buyers and multigenerational families are finding a way through it: buying a home that earns income, or that houses family, from the very first year.
House-hacking means living in part of a property while another part is rented or shared. With accessory dwelling units, often called ADUs, the strategy has become more practical than it once was. Here is how to think about it responsibly.
What House-Hacking Actually Means
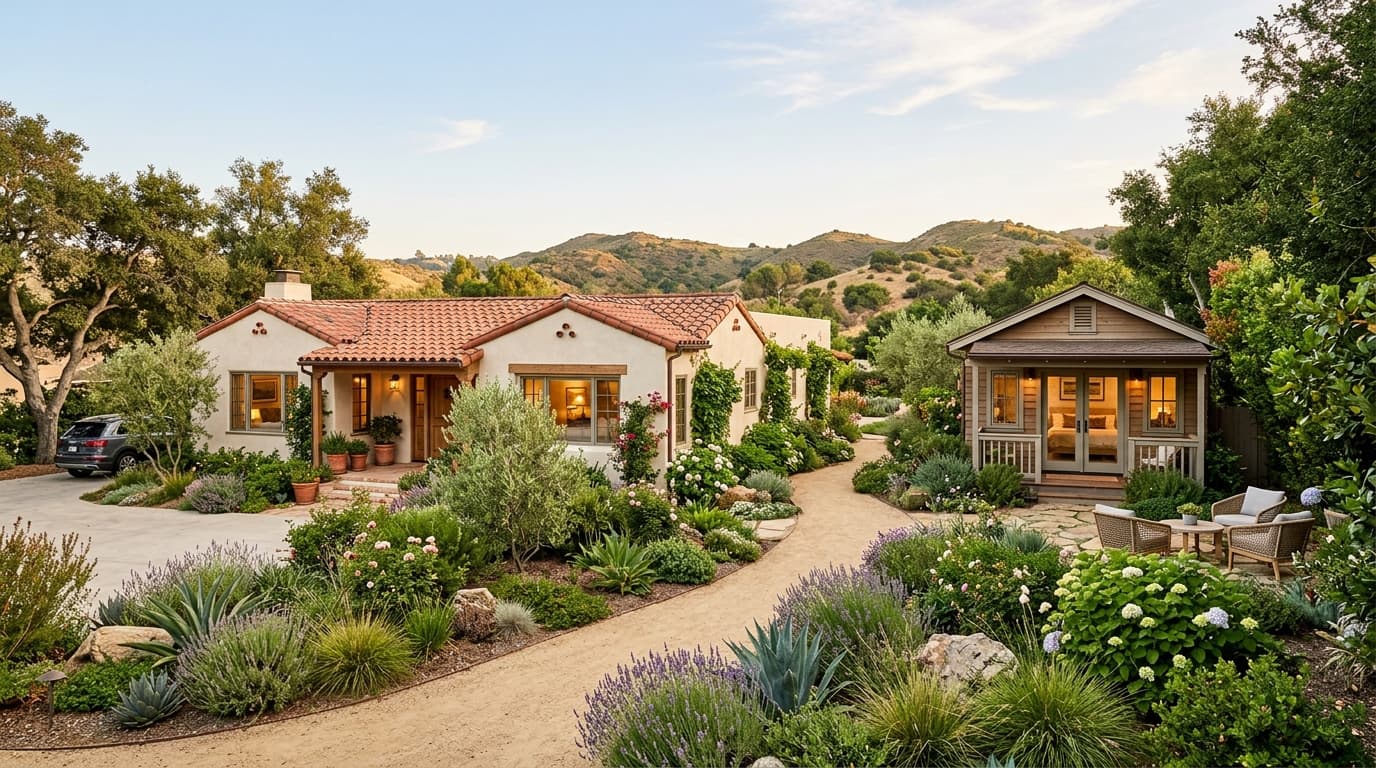
The idea is simple. Instead of paying a mortgage alone, you reduce your net housing cost by generating rent from part of the property. That might be a second unit, a converted garage, a detached backyard cottage, or a spare suite.
It is not free money. You become a landlord, with obligations, vacancy risk and maintenance. But the rent can meaningfully offset a mortgage in a high-cost submarket, where every dollar of relief matters.
Why ADUs Matter in High-Cost Markets
California has made it easier in recent years to add smaller secondary units on many residential lots. Rules can differ by city, lot size, zoning and whether a unit is attached or detached, so a general rule rarely tells the whole story. Always confirm requirements with the local planning department and your attorney before you buy or build.
In places such as Irvine and Arcadia, where purchase prices are high, an ADU can serve three different purposes:
- Rental income that offsets the mortgage.
- Multigenerational living, giving parents or adult children privacy under one roof.
- Flexibility, allowing a unit to switch between family and tenant over time.
Run the Numbers First
A hypothetical illustration: suppose a buyer's total monthly housing cost is a certain amount, and a unit could rent for a portion of it. The offset is the rent minus expenses attributable to the unit, such as insurance, utilities, maintenance and a vacancy reserve.
Be conservative. Use rent comparables you can verify, assume some empty months, and set aside funds for repairs. If the plan only works with perfect tenants and zero vacancy, it is too thin.
Financing and Qualification Considerations
Lenders treat rental income differently depending on the loan program and the documentation available. Some may count projected rent from an existing legal unit, others may be more cautious about a unit not yet built. Speak with a lender early so your purchase plan and your loan plan align.
Building a unit adds another layer: construction costs, permits, timelines and possible financing for the build itself. Get written bids and a clear scope before relying on the income.
Property Features to Look For
- A lot with usable space or an existing permitted secondary unit.
- Separate access and parking options for the unit.
- Utility connections and capacity that can support a second dwelling.
- A layout that allows privacy for both households.
- Verified permit history, not just a unit that exists informally.
Know the Tradeoffs
Shared property means shared lives. Consider privacy, tenant screening, landlord-tenant obligations, and how a rental affects your tax picture. Your CPA and attorney should weigh in before you commit.
Think About the Long Term
An ADU or second unit can change shape as your life does. A unit that houses a tenant today may house a parent next year, or a young adult returning home. When comparing properties, favor flexible layouts and sound construction, since both keep your options open. The best house-hacking plan is one that still works if your family circumstances change.
Next Step
If you are curious whether an ADU or small multi-unit property fits your goals, we invite you to book a private consultation with Yuanming Mao Private Real Estate Advisory. We will help you evaluate properties with real income potential, compare options across South Orange County and the San Gabriel Valley, and plan a purchase that fits your family.
This article is general education only and is not legal, tax, or lending advice. Consult your attorney, CPA, or lender for your situation.
Need an analysis calibrated to your property?
Request a confidential discussion with a specific decision framework.